
DAVAO CITY, Philippines—The Commission on Audit (COA) questioned a combined P115.376 million in personnel motivation incentives (PMIs) granted by Valencia City and the Bukidnon provincial government to appointive and elective officials and employees in 2025 audits.
COA questioned P31.230 million in incentives granted by Valencia City and P84.146 million released by Bukidnon province, saying the payments did not comply with applicable civil service rules, incentive policies and documentary requirements.
In Valencia, COA said the payments did not comply with civil service requirements and the city’s approved Program on Awards and Incentives for Service Excellence. The audit said it could not ascertain the validity, propriety and legality of the disbursements.
Auditors recommended that Valencia stop granting incentives and other benefits without sufficient legal basis, without prejudice to the recovery of amounts already received by the officials and employees concerned.
In Bukidnon, COA said the P84.146 million in personnel motivation incentives did not comply with policies and requirements governing employee incentives, leaving the validity, propriety and legality of the disbursements unascertained.
COA directed the provincial government to submit supporting documents and comply with applicable rules, warning that notices of suspension or disallowance could be issued if warranted.
The findings were contained in the 2025 audit reports of Valencia City, Bukidnon and Misamis Oriental, all of which received qualified opinions from COA. A qualified opinion means auditors identified matters that affected the fair presentation of the local governments’ financial statements.
The available reports do not cover all local government units in Northern Mindanao because COA had yet to post other 2025 audit reports as of Oct. 8.
Valencia City
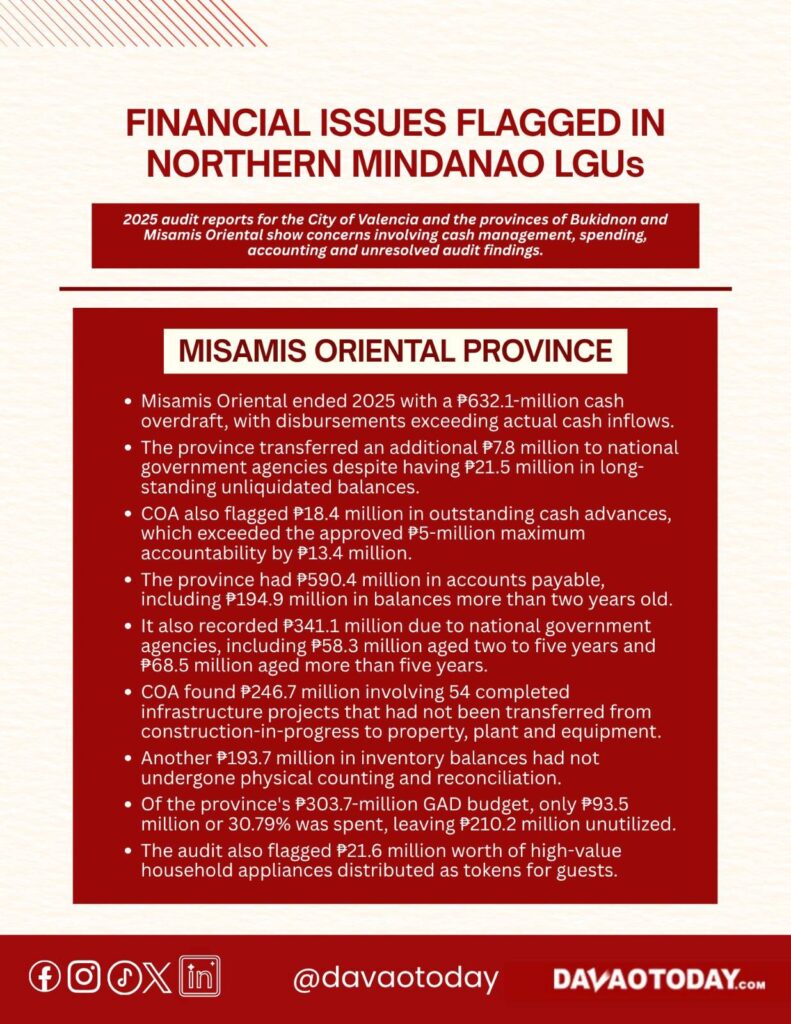
COA said it could not establish the existence and accuracy of Valencia City’s P704.629 million cash-in-bank balance as of Dec. 31, 2025.
The audit identified 522 unreconciled book items involving P94.284 million in additions and P67.721 million in deductions that remained unadjusted at year-end.
The city also reported 248 deposits in transit totaling P19.714 million, including items outstanding from three years to more than 20 years. It also had 50 stale checks worth P575,000, some of which were more than 10 years old, that had not been adjusted.
COA said the deficiencies affected the reliability of the city’s cash balance and were inconsistent with government accounting rules.
Auditors also found discrepancies in Valencia’s real property tax and special education tax receivables.
The amounts recorded in the books did not match the city’s list of delinquent real property taxpayers, resulting in a P160.324 million discrepancy. COA also found P113.462 million in receivables that had remained outstanding for more than 10 years.
The city also had P17.325 million in fiscal year 2023 performance-based bonus (PBB) payments with various deficiencies. COA said the payments were made before the Department of the Interior and Local Government issued a notice of eligibility, while P817,000 went to potentially ineligible recipients.
The total payment exceeded the recognized liability for the benefit by P1.525 million and exceeded the appropriation for the purpose.
COA’s follow-up on previous audit recommendations showed that only 32 of 101 recommendations issued from 2013 to 2024 had been fully implemented. Sixty-nine remained unimplemented, including 20 reiterated in the 2025 report.
Bukidnon
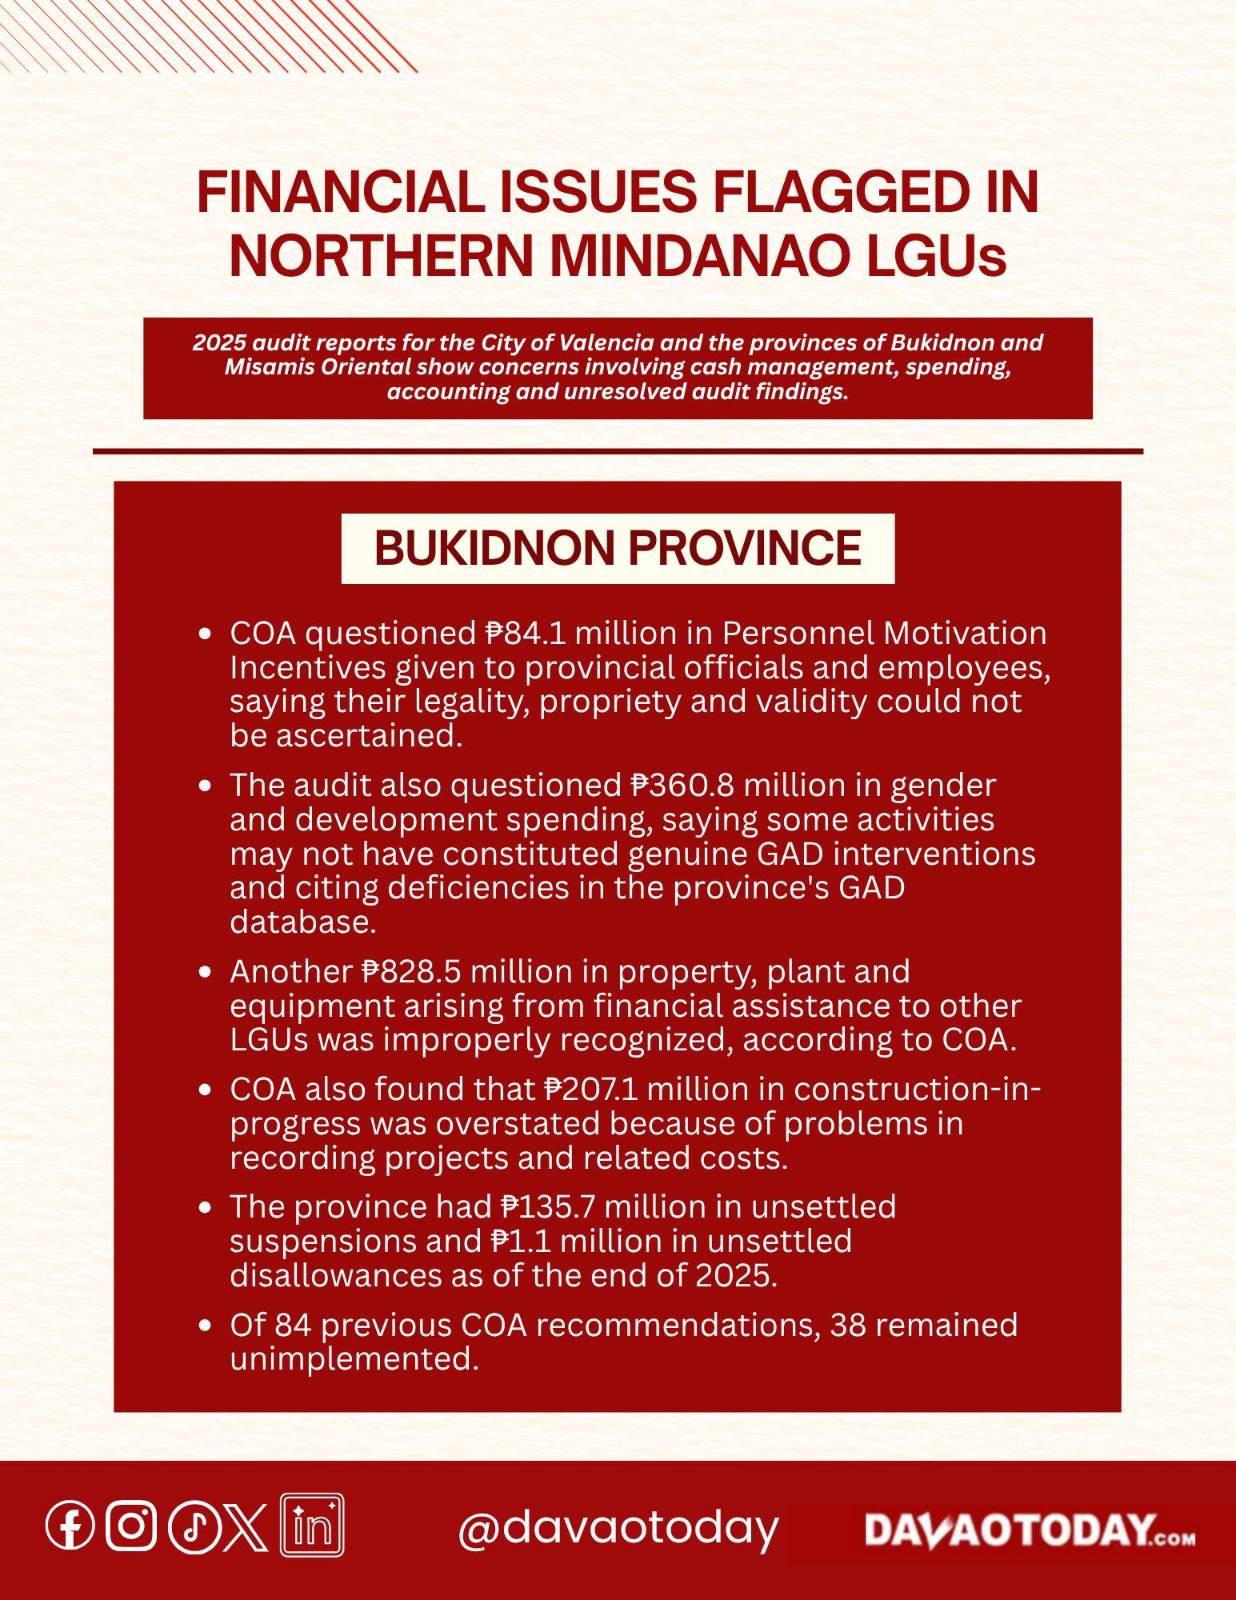
COA also questioned the Bukidnon provincial government’s use of P360.827 million for gender and development programs, projects and activities.
The audit said activities identified in the 2025 Gender and Development Plan and Budget might not qualify as genuine gender and development interventions. It also found that the province had not prepared its gender and development database in accordance with government guidelines.
The deficiencies raised questions about whether the spending contributed to the intended objectives of promoting gender equality and women’s empowerment, COA said.
Auditors also found accounting problems involving property and infrastructure.
Property, plant and equipment resulting from financial assistance to other local governments had an aggregate net book value of P828.478 million but had been improperly recognized, resulting in an overstatement of property, plant and equipment and government equity accounts.
Completed projects worth P207.061 million also remained under construction in progress, overstating that account.
At the end of 2025, the province had P135.736 million in unsettled suspensions and P1.072 million in unsettled disallowances from previous years.
Of 84 prior-year audit recommendations reviewed by COA, 46 had been fully implemented and 38 remained unimplemented. Nineteen of the unimplemented recommendations were reiterated in the 2025 audit.
The findings came despite Bukidnon reporting P24.702 billion in assets, P2.870 billion in liabilities and a P1.650 billion surplus in 2025. The province reported P6.528 billion in revenue and P4.696 billion in expenses during the year.
Misamis Oriental
Misamis Oriental’s audit raised concerns over cash management, fund transfers, infrastructure accounting and outstanding liabilities.
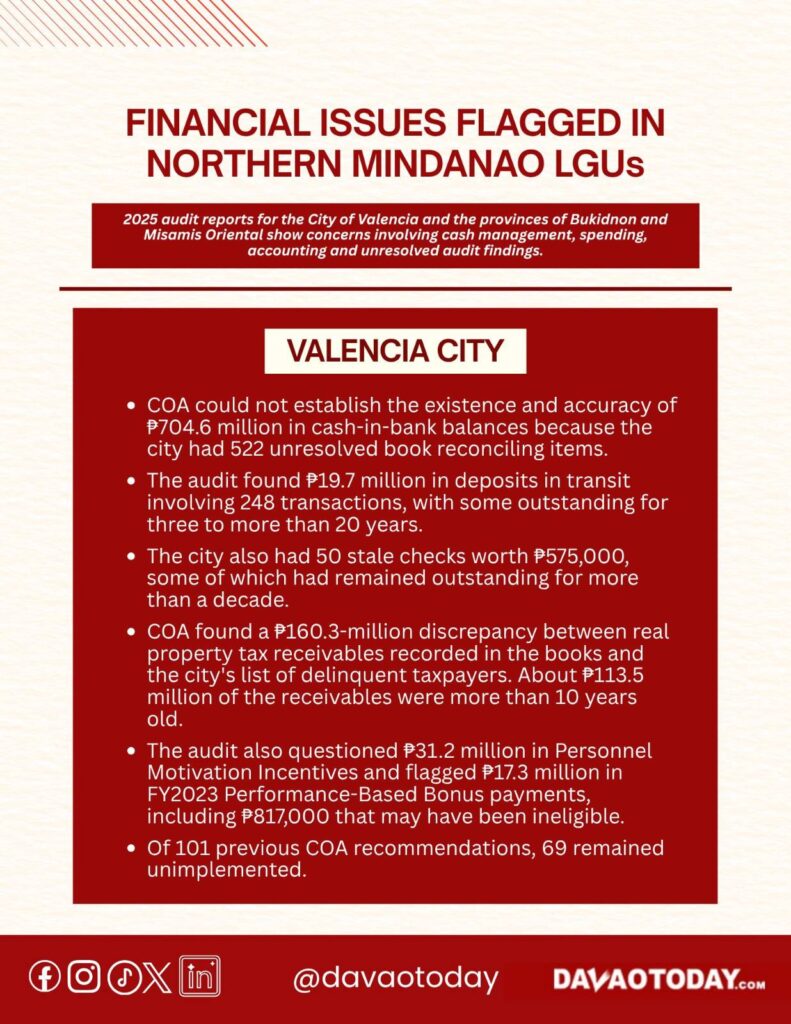
COA found that the provincial government had a P632.050 million cash overdraft as of Dec. 31, 2025, after disbursements exceeded actual cash inflows.
Auditors said the situation adversely affected fiscal stability and budget execution and violated the Local Government Code. COA recommended that the province rationalize its budget based on reasonable income estimates, improve revenue collection and exercise fiscal control based on actual revenue and borrowings.
The province also granted P7.844 million in additional fund transfers to national government agencies despite P21.548 million in long-standing unliquidated balances.
COA said the practice indicated weak controls over the liquidation and certification of previous fund transfers. It recommended requiring actual liquidation before approving or releasing subsequent transfers.
Another finding involved P18.449 million in outstanding cash advances granted to a special disbursing officer despite an earlier unliquidated cash advance.
The amount exceeded the officer’s P5 million maximum approved accountability by P13.449 million, exposing government funds beyond the coverage of the officer’s fidelity bond, COA said.
The province’s P341.124 million account due to national government agencies also included long-outstanding and unliquidated balances. Of the total, P58.334 million had been outstanding for two to five years, while P68.549 million had remained outstanding for more than five years.
COA said delays in monitoring, reconciliation and coordination affected the validity of the liabilities and the fair presentation of the province’s financial statements.
The province also reported P590.379 million in accounts payable, including P194.853 million in balances more than two years old that had not been reverted to the General Fund’s unappropriated surplus pending verification of supporting documents.
COA said the condition made the validity and correctness of the liabilities doubtful.
Auditors also scrutinized infrastructure and inventory records.
COA found that 54 completed infrastructure projects worth P246.661 million had not been transferred from construction in progress to the appropriate property and equipment accounts. The accounting errors included a P195.853 million overstatement of construction in progress.
Inventory balances totaling P193.731 million were recorded without a physical count or reconciliation of records, exposing the financial statements to a high risk of material misstatement, COA said.
The audit also found that the province approved a P303.687 million gender and development budget but spent only P93.517 million, or 30.79%, by the end of 2025, leaving P210.170 million unutilized.
COA also flagged P21.595 million spent on high-value household appliances distributed as tokens for guests under the project, “Token for Guest in Various Events and Activities.” The items were customized with the “Paglaum” logo and an image associated with a public official.
More audits pending
The available reports do not cover all local government units in Northern Mindanao because COA had yet to post other 2025 audit reports.
The findings are based only on 2025 executive summaries that COA had posted for Northern Mindanao local governments as of Oct. 8.
The reports show recurring concerns involving financial reconciliation; accounting for assets and liabilities; cash advances; fund transfers; incentive payments; and implementation of prior audit recommendations.
COA also had not posted the remaining 2025 audit reports for other Mindanao local governments as of Oct. 8. (davaotoday.com)


